DOI: https//doi.org/10.13037/gr.vol36n109.6019
|
Received: 10/05/2019 | Accepted: 28/04/2020 |
A sustentabilidade e a transparência influenciam na tomada de decisão do investidor brasileiro? Um estudo com alunos universitários de gestão e negócios
Do sustainability and transparency influence the decision-making process of the Brazilian investor? A study with business management university students
|
Dannie Delanoy Carr Quirós[1] |
Fernanda Maciel Peixoto[2] Orcid: https://orcid.org/0000-0002-0969-7567
|
|
André Francisco Alcântara Fagundes[3]
|
Cláudia Olímpia Neves Mamede Maestri[4] Orcid: http://orcid.org/0000-0002-6978-5219 |
Resumo
A literatura aponta que a divulgação dos dados contábeis é essencial para a tomada de decisões de investimento. No entanto, cada indivíduo processa de forma distinta a informação financeira para tomar decisões (HENDRIKSEN; VAN BREDA, 1999). Argumenta-se que é racional investir em empresas sustentáveis e transparentes dado que elas tendem a apresentar melhor performance (BODHANWALA; BODHANWALA, 2018). Considerando esse panorama teórico, este estudo buscou investigar os possíveis efeitos que a sustentabilidade e a transparência podem ter sobre a tomada de decisão dos investidores que investem em ações. Para isso, foi desenvolvido um experimento por meio de uma pesquisa de opinião aplicada a estudantes universitários. O método de análise envolveu análise bivariada e regressão múltipla cross-section. Constatou-se que a sustentabilidade e a transparência não influenciaram a tomada de decisão de investimento. No entanto, percebeu-se uma relação entre o volume de recursos investido e a idade do investidor.
Palavras-chave: Sustentabilidade. Transparência. Decisão de Investimento.
Abstract
The literature points out that the disclosure of accounting information is essential for making investment decisions. However, each individual processes the financial information differently to make decisions (HENDRIKSEN; VAN BREDA, 1999). It is argued that is rational to invest in sustainable and transparent enterprises as they tend to perform better (BODHANWALA; BODHANWALA, 2018). Considering this theoretical panorama, this study sought to investigate the possible effects that sustainability and transparency can have on the decision-making of investors who invest in shares. For this, an experiment was developed through an opinion survey applied to university students. The method of analysis involved bivariate analysis and multiple cross-section regression. It was found that sustainability and transparency did not influence investment decision making. However, there was a relationship between the volume of funds invested and the age of the investor.
Keywords: Sustainability. Transparency. Investment Decisions.
INTRODUCTION
One of the main goals of financial disclosure is to provide information for decision-making. Each firm is different regarding their financial disclosure policies and the individuals who are part of these films process the information they receive in different ways to make decisions (HENDRIKSEN; VAN BREDA, 1999).
Traditionally, when we think about Finance, we believe it is based on rationality for decision-making. In the past three decades, the field of Finance has developed based on the assumptions that other people make rational, unbiased decisions in their predictions about the future (BARBERIS;THALER, 2003). However, this premise, which has been considered fundamental in supporting modern economic and financial theory, is not seen as the single one possible for some authors. There are indications of the existence of limited rationality due to a series of behavioral trends, which often lead to decisions made in an unconscious and innate way by humans (Ricciardi e Simon, 2000).
In 1957, Simon was the pioneer in recognizing the limited cognitive capacity of the human mind when he introduced the concept of bounded rationality. Using Simon’s (1957) notion of bounded rationality, Kahneman e Tversky (1979) sought to connect economy, finance and behavioral aspects in order to analyze decision-making under risk. In the seminal studies of Kahneman e Tversky (1979), the authors approached the theme of “Behavioral Finance”. One of their most relevant studies was the article “Prospect Theory: an analysis of decision under risk”, published in1979, which criticizes the expected utility theory as a descriptive model for decision-making under risk and presents an alternative model called prospect theory, which demonstrates evidence of the limited rationality of humans for decision-making under risk (LUPPE; ANGELO, 2010).
The literature shows that decision-making for investments involves several factors to be considered by investors when they allocate their capital (Tahir e Brimble, 2011). Therefore, there have been various efforts to explain behavioral phenomena and how these factors may affect decision-making for investments, such as the effects of first investment experiences on future investments (PAPADOVASILAKI et al., 2015), issues regarding religion (TAHIR; BRIMBLE, 2011), sensitivity to gains, losses and risks (ZHOU; PHAM, 2004), and disclosure of environmental information (ALVES; BORBA, 2010; BORBA et al., 2012; MILNE; PATTEN, 2002).
In addition, according to Santos (2017), investors do not have access to the same information and have different degrees of education, past experience, demographic characteristics and other factors which lead to the existence of different profiles of investors, affecting the way they invest. These behaviors of investors may be grouped through profile classifications, and many studies have identified a predominance of profiles who tend to avoid risky operations, that is, conservative or moderate profiles (ALMEIDA; CUNHA, 2017; ALVES, 2012; HAUBERT; DE LIMA; HERLING, 2012; JUNIOR; SOUZA; SANTOS, 2015; MAUSS; DELATORRE, 2012; RAMBO, 2014; ROLDAN; ROCHA, 2004). This type of behavior has been related to the lack of knowledge by the Brazilian investor (ALMEIDA; CUNHA, 2017; ALVES, 2012; GASPAR; OSÉS, 2007; RAMBO, 2014) and to the cognitive biases (BOGEA; BARROS, 2008; COTRIM, 2014; SANTOs, 2017) that may influence the decision-making process.
Despite the existence of some studies about the profiles of investors as presented above, the use of experimentation in finance to study the relationship between sustainability and transparency and the decision-making of investors is still a somewhat unexplored field in the literature, according to Borba et al. (2012). According to Bodhanwala e Bodhanwala (2018), that is because it is rational to invest in sustainable firms that tend to have a higher profitability level, since some studies have perceived a positive relationship between sustainability and profitability. In addition, Bona-Sánchez et al. (2017) argue that there is a positive relationship between sustainability and the disclosure of results (transparency).
After acknowledging this background and these gaps in the literature, the research problem defined for this study is: Can sustainability and transparency affect share investment decision-making? In case they can, what is this relationship like? To answer these questions, we carried out an experiment through an opinion survey where different scenarios are presented, with information regarding an investment opportunity and complementary data on sustainability and transparency, directing it to respondents who have financial knowledge and who have bank accounts. The main goal was to investigate the potential effects sustainability and transparency might have on the decision-making of investors at the moment when they allocate their resources in variable income (shares).
The use of the experiments methodology has limitations such as sample size and external validity (TAHIR; BRIMBLE, 2011). However, this method brings its own contributions, and it is important because it complements the findings of quantitative studies on finance and overcomes some of their limitations (DUXBURY, 2015). According to Borba et al. (2012), it is essential to inform external clients or investors in order to motivate them to invest on a certain firm, and it is necessary to listen to their opinion about what they consider important in their decision-making process when selecting assets. In addition, we perceive a detachment between modern finance theory and practice in financial decisions, and behavioral finance may be the answer and an alternative to explain the behavior of the economic agents (KIMURA; BASSO; KRAUTER, 2006).
This research contributes to the study of Brazilian investors and their decision-making process for investing. We adopted a methodology that is not often used in corporate finance, seeking to connect the theory to the financial reality of the respondents through experimentation in the Triângulo Mineiro region in Minas Gerais, Brazil, which makes the study regional in nature.
THEORETICAL FRAMEWORK
Investment decisions
Several studies have sought to understand which factors affect the decision-making of individual investors. Papadovasilaki et al. (2015) investigated the role of the first investment experiences in the decision-making of future investments in the USA. They carried out an experiment with two groups of respondents who had to choose between investing in options, with or without risk, during twenty periods. The first four (4) periods corresponded to the ‘first experience’ or the ‘initial experience’; at that moment, one group experienced a boom in the market, and the other group faced a crisis. The results of this experiment showed that the participants in the crisis scenario tend to obtain less risky assets in the periods after the crisis when compared to the people who experienced the scenario with no crisis, demonstrating that the first experiences (initial experiences) of investors have a significant impact in their future decision-making (PAPADOVASILAKI et al., 2015).
Regarding the access to information and the level of risk taken by the investors, Kaufman e Weber (2013) identified that additional information (complementary information that firms provide) lead to more investor confidence, allowing them to take higher risks in their investments.
Paraboni et al. (2018) sought to understand the perceptions of liquidity and risk in the American, Chinese and German markets through the assumptions of the Prospect Theory. Their findings indicated that, when there is low perceived liquidity in the market, investors reduce the negotiated volume due to the increase in risk, and that in the opposite scenario, when there is high perceived liquidity, there is an increase in negotiations due to the decrease in risk.
Regarding the use of different types of information to make investment decisions in the stock market, Khan, Tan and Chong (2017) indicate that apparently, in Malaysia, the technical and fundamental indicators are considered important by investors, but in practice are not used to make decisions. According to the study, in practice, investors use the share’s return history, analyze the investment decisions of other investors and other markets, the specialized press, and stock exchange bulletins.
Regarding the use of environmental information for investment decision-making, Milne and Patten (2002) carried out an experiment with 76 accountants of firms in the chemistry sector (an industry sector which causes high environmental impact). The respondents had to allocate an amount of money to an investment opportunity, while half of the respondents received additional environmental and ecological information and the other half did not, seeking to determine whether the first group would place more resources in this option than the second group. The results showed that the voluntary disclosure of environmental information significantly and positively affects the decision-making of those accountants when they plan to invest in the long term; however, this did not happen when the accountant intended to invest in the short term. That happened because the disclosure of environmental information compensated for the negative reactions these accountants had due to disclosure of significant debt in the firm.
Still regarding environmental information, in Brazil, Alves and Borba (2010) found that, for a group of graduate students in Accounting, the environmental accounting information is important for decision-making in investments. In their experiment, the disclosure and access to environmental information affected the investment decision of the respondents. Alves and Borba (2010) followed the methodology of Milne and Patten (2002) and concluded that, for 59% of their sample, environmental information was important when investing. This result was also shown in the higher average investment received by firm B (the firm or option with the highest disclosure of information related to the environment), both in the long term and in the short term. In a related study with identical methodology, Borba et al. (2012) found that, for 79% of their sample of finance professionals, the investment option that had the highest disclosure of environmental information received the highest allocation of resources.
Regarding the perception of returns, Steinhorst and Bahrs (2014) carried out an experiment in Germany between 2011 and 2013 to investigate the investment decisions of farmers and traders of agricultural products. The individuals selected had to classify different investment opportunities according to their personal perspective. The results showed that the participants were willing to receive lower income rates as long as the returns were constant.
Regarding the sensitivity to gains and losses, Zhou and Pham (2004) carried out an experiment with 198 respondents to evaluate the investment opportunities with different rates of gains and losses. The participants had to indicate their intention of investing in different investment opportunities. The main results showed that investors have different degrees of sensitivity to gains, losses and risk, depending on the financial product they are investing on. In other words, sensitivity to gains and losses depends, in principle, on the financial asset (ZHOU; PHAM, 2004).
Pimenta, Borsato and Ribeiro (2012) carried out a research with a sample of individuals enrolled at the Minas Gerais Association of Capital Market Investment Analysts and Professionals (APIMEC-MG) and with individuals enrolled at TBC Investimentos (a stockbroker in the Triângulo Mineiro region). They used an online questionnaire. Their results demonstrated that differences in opinion, style and perception of reality, motivated by personal and investment characteristics and by the confidence bias of the agents, have a relevant impact on decision-making.
Santos and Barros (2011) developed a study seeking to understand the rationale of the decision-making process of 641 Brazilian participants, who answered an online questionnaire. The study showed that both reason and emotion affect most of the respondents, and the decision-making process in influenced by factors such as differences in perception, personality and capability of evaluation. In addition, the respondents believe that their financial behavior is more rational than that of their peers. Furthermore, the investment decisions were influenced by characteristics such as demographics, sex, income, age, and education level, and men were more likely to take risks (more aggressive profile) than women.
Seeking to understand whether religion has an impact in decision-making for investments, Tahir and Brimble (2011) carried out an experiment with a random sample of 446 participants (210 Muslims and 236 non-Muslims). In the experiment, all participants invested in a list of opportunities in a fictional portfolio, then explained their decisions, and the group of Muslims answered questions about the rationale of the principles of Islamic law. The results indicated that religion tends to influence the decision-making of the Muslim respondents; however, the influence depends on the amount of beliefs each individual has.
In summary, regarding investment decisions, according to the findings of Kimura, Basso and Krauter (2006) , human beings tend to make decisions that are contrary to the postulates of the expected utility theory, which leads to non-rational decisions by investors. Behavioral finance may be used as an alternative to explain these decisions. In addition, different perception biases for investment decisions are maintained regardless of aspects related to the evolution of the market, the culture or the nationality of individuals.
Investment decisions, sustainability and transparency
As discussed above, investors are influence by several socio-demographic, behavioral, and macroeconomic factors when making investment decisions. Some studies indicate the investors are interested in allocating resources in sustainable and transparent firms because such firms tend to to provide a higher level of profitability (BODHANWALA; BODHANWALA, 2018).
The effects of the sustainable measures taken by the firms on their economic results raises a debate of opposing views. There are studies which state that the adoption of these practices stimulates development, and other studies which indicate that sustainable measures generate unrecoverable costs for the firms (BARAKAT et al., 2016). Several studies in Brazil and in other countries sought to associate sustainability practices with firm performance analyzing different samples: Bodhanwala and Bodhanwala (2018) - Indian firms; Schonborn et al (2018) - German firms; Barakat et al. (2016) - Brazilian firms; however, they did not find a relationship between sustainability and performance. In addition: Paica et al. (2019) – Brazilian small and medium enterprises; Ribeiro, Alves, Taffarel and Menon (2017) – Brazilian firms in the electricity sector.
Transparency can be defined as a firm’s availability of information to internal and external users, as indicated by Bushman, Piotrosk and Smith (2004). According to Lin, Liu and Noronha (2016) in a study developed in China, good corporate governance practices favor the transparency in the financial information disclosure of firms. In that country, according to Bushman et al. (2004), the understanding of transparency is important in order to promote business ethics, integrity and sustainability in the capital market. In turn, Corporate Sustainability is the set of measures a firm takes in order to respect the environment and the sustainable development of the society (LAVILLE, 2009).
Some studies sought to associate transparency and sustainability or transparency with corporate social responsibility (CSR), a construct that interfaces with corporate sustainability in terms of involving the social, economic and environmental dimensions. Nair et al. (2019) investigated the relationship between financial transparency and corporate social responsibility in a sample of 100 Indian private firms in the period from 2014 to 2017. The authors found that, during the legal regime of mandatory disclosure in India, the disclosure of Corporate Social Responsibility improve financial transparency.
Higgins, Tang and Stubbs (2019) analyzed the sustainability reports produced by firms and financial services in Australia. They sought to evaluate, through a content analysis, the clarity, accuracy and transparency of these sustainability reports. The found serious limitations in the information reported by the firms, indicating information duplicity, lack of clarity and accuracy issues in the sustainability information.
Regarding research on investment decisions, transparency and sustainability, the following experimental studies were used as a base for constructing our investigation: Alves and Borba (2010), Borba et al. (2012) and Milne and Patten (2002). These studies were used as a base because they had a similar goal to our research, which is investigating how the presence of a certain piece of information (observation or independent variable) affects the decision-making of investors.
The observation (or independent) variable in these studies was the disclosure of environmental information and its influence on the decision-making for investments. These experiments were applied mostly to university studies and used financial information that was either real or corresponded to public firms. In general, the basic experiments for this study can be described as follows: the participants were divided into two groups and had to allocate an X amount of resources to a certain option. One group had access to information related to the observation variable (experimental group), and the other did not (control group). To produce the results, the averages of the investments made by each group were compared in order to determine whether there was an effective difference in the investment average between those who had access to the observational information and those who did not.
Based on the studies mentioned, our goal is to investigate, in the Brazilian context, how investors are influenced by the transparency level of firms. In addition, there is a lack of studies in Brazil seeking to understand how investors can be influenced by the level of sustainability of the firms when purchasing shares.
Considering what was presented above, we adopted the following hypothesis for this study:
Hypothesis 1: Corporate sustainability positively influences the allocation of resources in shares.
Hypothesis 2: Transparency positively influences the allocation of resources in shares.
Hypothesis 3: Sustainability and transparency, considered simultaneously, may positively influence the allocation of resources in shares.
METHODOLOGY
Design of the experiment
The experiment in this study consisted of 4 tests or scenarios to evaluate whether sustainability and/or transparency influence the behavior of investors when deciding the amount to invest in the shares presented to them. The participants evaluated shares in the following four different scenarios, which were randomly distributed to respondents: (1) no information on transparency or sustainability; (2) information on transparency; (3) information on sustainability; and (4) information on both sustainability and transparency. Before the specific scenarios, the experiment involved the presentation of a table containing real information regarding shares with a fictional firm name. Afterwards, the respondents had to indicate the amount of money to invest in the shares presented to them, assuming they had R$ 100,000.00 available to invest. Then, each individual had to justify their decision and answer a series of complementary questions aiming to classify their socio-demographic profile. We sought to analyze the decision-making of the participants in order to assess how the independent variables might affect their decision.
The independent variables in the experiment were the absence/presence of information on transparency and/or sustainability, and the dependent variables tested were the amount to allocate, the attractiveness of the shares, and the willingness to recommend the shares to a friend. In addition, we asked questions related to the investor’s profile, seeking to better categorize the profile of the participants.
Questionnaire explanation
The questionnaire, like any other document related to the research or research tool, can be requested by email to the authors. The questionnaire used in the experiment was divided into four parts. Part I contains a description of the questionnaire for the respondents, the informed consent form, and questions regarding the bank account.
Part II contains the table with the share information, the question about the amount to invest in the share and the request for justification. A hypothetical scenario was presented to the respondents in which they received R$ 100.000,00 to invest in the shares presented to them. The table contained real financial information consisting of the four-trimester average of firms belonging to the Bovespa Index, including the third trimester of 2017, the fourth trimester of 2017, the first trimester of 2018 and the second trimester of 2018, collected from the Economática database. The data on the four last trimesters were included so that respondents could see the evolution in the performance of the shares over time. The financial indicators presented in this table were: (a) net income, (b) profitability, (c) debt, (d) revenue, (e) revenue growth, (f) market value, (g) profit per share, (h) share prices over the year, (i) volatility of returns in the period, (j) book value per share, (k) sales per share, (l) EBITDA, (m) EBITDA margin and (n) dividends per share.
These financial characteristics were chosen for three reasons. The first reason is based on the application of a simplified questionnaire (pre-test) during the 3rd Edition of the Financial Education Week at UFU (Uberlândia Federal University), which involved items or aspects that the participants considered more relevant when investing, through a Likert scale and with the possibility to add new characteristics that they considered important and were not in the scale. The public who participated of the event and answered the questionnaire are mostly people connected to the university, with considerable financial education and interested in the stock market. The second reason is the literature, especially the base studies that used these or related characteristics. The third reason involved the review and suggestions made by an investment advisor of a stockbroker in the Triângulo Mineiro region, who, in addition to reviewing the variables chosen for the study, made new suggestions and reviewed and checked the questionnaire in order to ensure its quality, validity, and that the experiment was as close as possible to the reality of the investors.
The values of the variables used correspond to the average of those variables in firms belonging to the Ibovespa. Ibovespa is a performance index composed of the B3 firms with the largest volume of negotiation in recent months (B3, 2019). The firms in this index were chosen because most of them are organizations classified under the New Market (firms with good corporate governance practices) and under the ISE (Corporate Sustainability Index). In addition, these firms were chosen in order to avoid any outlier in the data (which could have happened with data from a single firm) that could affect the decision-making of the investors.
The information on sustainability and transparency was supported by the three reasons stated above and also based on the information present in the forms filled by the firms belonging to the ISE and the IGC (Corporate Governance Index). All this data was presented under the fictional firm name GAMBO CELULOSE S.A.
Still during Part II, the research participants were requested to indicate the amount they would be willing to invest in that share. Lastly, an open question was made so that individuals could explain the reasons for making the investment.
In Part III, we used the Likert scale to investigate the investor’s profile (conservative, aggressive or moderate), the attractiveness of the share, the willingness to recommend the share, and previous experiences and knowledge regarding investment in shares. We asked participants about their opinion regarding their self-confidence, optimism and risk aversion as characteristics to define their profile. Attractiveness in the long and short term was included in order to measure the level of attraction perceived by the person for the share. Willingness to recommend the share to a friend was included in order to measure share recommendation and whether the participant had knowledge about shares. Lastly, we asked whether the participants had invested or currently invested in shares, their experience regarding investments of that nature, and the way they invested in shares, whether without assistance, using the services of a stockbroker or specialist, or following the suggestions of their bank manager.
Part IV of the questionnaire included socio-demographic questions for general classification of the respondents, such as age, birth date, marital status, state of residence, level of education, approximate monthly income, number of people supported by their income and number of children.
Sample
The research had 419 replies, and we removed replies that had too many missing values and answers that indicated that the respondent was not interested in participating in the study. This filtering of the replies reduced the research sample to 383 respondents, which corresponds to more than 91 valid replies for each study scenario or for each study group. The respondents are Brazilians majoring in Business Administration, Economics, Accounting and Information Management at an HEI (Higher Education Institution) in the Triângulo Mineiro region. University students were chosen because most of the literature uses university students to make experiments about investments or related to financial education, such as Almeida and Cunha (2017); Alves and Borba (2010); Borba et al. (2012); Haubert , de Lima and Herling (2012); Junior, Souza and Santos (2015); Tahir and Brimble (2011); Vieira, Bataglia and Sereia (2011). In addition, according to Almeida and Cunha (2017), university students have better financial education than the national average and are often used as “proxies” for investors. Respondents were required to have a bank account to participate in the study because we understand that an individual who has a bank account is more likely to invest their surplus capital.
Data collection
The data was collected through a physical questionnaire applied to groups of students in undergraduate and graduate courses in Business Administration, Accounting and Information Management at an HEI in the Triângulo Mineiro region during October and November, 2018. The questionnaires were interspersed according to the four scenarios of the experiment and randomly distributed to each student in each group, aiming to maintain the homogeneity of the participants.
The respondents were divided into 4 different groups, with one control group and three experimental groups, that is, one group for each of the four scenarios of the experiment. Group 1 (the control group) received the general information regarding the share (scenario 1). Group 2 (experimental - sustainability) received the same information as the control group with the addition of information on sustainability (scenario 2). Group 3 (experimental - transparency) received the same information as the control group with the addition of information on transparency (scenario 3). Lastly, group 4 (experimental - sustainability and transparency) received the same information as the control group with the addition of information on sustainability and transparency, which was the same information received by groups 2 and 3, respectively (scenario 4). It is important to clarify that each respondent participated in only one of the four study groups, that is, each respondent participated in only one scenario.
Data analysis
For the data analysis, we used descriptive statistics, non-parametric tests such as the Kruskal-Wallis test and the Mann-Whitney test, and multiple regression. These tests are recommended when the data does not comply with the assumptions of the parametric tests based on normal distribution, according to Field (2009). The data in this research does not follow a normal distribution and there is heterogeneity in the variances.
To study the influence of each variable on the investment decision, we used a multiple regression containing the variables represented in Table 9, as follows:
|
Table 9 - Research variables |
||
|
Variable |
Description |
Measurement |
|
Investment (INV) |
How much was invested in the share |
Amount invested |
|
Type of Share (TYP) |
A dummy for each of the scenarios of the share |
0 = no information on sustainability or transparency 1 = information on sustainability 2 = information on transparency 3 = information on both sustainability and transparency |
|
Experience (EXP) |
A dummy for the respondent’s experience with investment in shares. |
0 = EXP < 2 (Likert scale) 1 = EXP 2 (Likert scale) |
|
Knowledge (KNO) |
A dummy for the respondent’s level of knowledge about “investment in shares” |
0 = KNO < 2 (Likert scale) 1 = KNO > 2 (Likert scale) |
|
Education level (EDU) * |
A dummy for each education legal |
0 = Completed secondary education 1 = Completed undergraduate education 2 = Completed graduate education |
|
Income (INC) * |
A dummy for each income category |
0 = Up to 3 times the minimum wage 1 = Between 3 and 5 times the minimum wage 2 = More than 5 times the minimum wage |
|
Sex (SEX) |
A dummy for each sex |
0 = Female 1 = Male |
|
Age (AGE) |
The participant’s age |
The participant’s age |
|
Note. * The categories Education Level and Income are different from the categories shown in the questionnaire because they were simplified in order to facilitate the econometric analysis. Source: Elaborated by the authors. |
||
The variables on Table 9 composed the following multiple regression model:
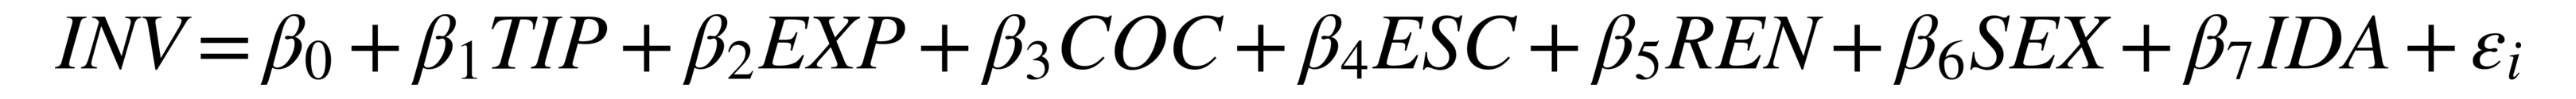
Where in the model:
β = coefficients associated with the independent and control variables;
ε = error term of the equation
RESULTS
Descriptive Analysis
Table 10 shows the description information of the scalar variables (continuous) in the study, which were Investment and Age, separated according to each research scenario.
|
Table 10 - Descriptive analysis of the scalar variables |
|||||
|
Shares with no information on sustainability or transparency |
|||||
|
Variable |
N |
Minimum |
Maximum |
Average |
Standard Deviation |
|
Investment |
99 |
0 |
100000 |
28869.7000 |
26100.1860 |
|
Age |
82 |
18.00 |
50 |
25.4878 |
7.0154 |
|
Shares with information on sustainability |
|||||
|
Investment |
96 |
0 |
100000 |
28442.7100 |
25110.1650 |
|
Age |
83 |
17 |
63 |
25.7470 |
7.4586 |
|
Shares with information on transparency |
|||||
|
Investment |
97 |
0 |
100000 |
24332.3700 |
24220.8380 |
|
Age |
83 |
18 |
50 |
25.3133 |
6.6990 |
|
Shares with information on both sustainability and transparency |
|||||
|
Investment |
91 |
0 |
100000 |
28716.4800 |
27711.0300 |
|
Age |
86 |
18 |
55 |
25.4651 |
6.9531 |
|
Note. Meaning of the abbreviations: INV = Investment; AGE = Age Source: Research results. |
|||||
Table 10 shows that, by a small margin, the scenario with no information on sustainability and transparency received the highest average investment, and the scenario that only showed information on transparency received the lowest average investment. On the other hand, age remained constant throughout the different scenarios.
Table 11 shows the results of the correlation matrix used to measure the association between variables.
|
Table 11 - Correlation Analysis |
||||||||
|
|
INV |
TYP |
EXP |
KNO |
EDU |
INC |
SEX |
AGE |
|
INV |
1.0000 |
|
|
|
|
|
|
|
|
TYP |
-0.0214 |
1.0000 |
|
|
|
|
|
|
|
EXP |
0.0338 |
0.0174 |
1.0000 |
|
|
|
|
|
|
KNO |
0.0473 |
0.0055 |
0.6054*** |
1.0000 |
|
|
|
|
|
EDU |
-0.1012** |
-0.0401 |
0.0918* |
0.1263** |
1.0000 |
|
|
|
|
INC |
-0.0834 |
-0.0880 |
0.0915* |
0.0269 |
0.3577*** |
1.0000 |
|
|
|
SEX |
-0.0613 |
-0.0065 |
-0.2441*** |
-0.1802*** |
0.0263 |
-0.0853 |
1.0000 |
|
|
AGE |
-0.1422*** |
-0.0080 |
0.1455*** |
0.1524*** |
0.6832*** |
0.3788*** |
-0.0506 |
1.0000 |
|
Note. Meaning of the abbreviations: INV = Investment; TYP = Type of share; EXP = Experience; KNO = Knowledge; EDU = Education Level; INC = Income; SEX = Sex; AGE = Age. The asterisks correspond to the level of significance; * corresponds to 10%, ** corresponds to 5% and *** corresponds to 1%. Source: Research results. |
||||||||
Table 11 shows mainly a potential association between the variables experience and knowledge with the rest of the variables. Table 12 presents the results of the multicollinearity test to verify whether the associations shown in the correlation matrix persist.
|
Table 12 - Multicollinearity Analysis |
||
|
Variable |
VIF |
1/VIF |
|
TYP 1 |
1.57 |
0.636659 |
|
TYP 2 |
1.52 |
0.656370 |
|
TYP 3 |
1.54 |
0.649596 |
|
EDU 1 |
1.59 |
0.627806 |
|
EDU 2 |
1.66 |
0.601197 |
|
INC 1 |
1.19 |
0.842533 |
|
INC 2 |
1.37 |
0.728614 |
|
EXP |
1.72 |
0.583006 |
|
KNO |
1.68 |
0.594889 |
|
SEX |
1.11 |
0.900782 |
|
AGE |
2.01 |
0.497344 |
|
VIF Average |
1.52 |
|
|
Note. Source: Research results. |
||
Table 12 shows the VIF value of all variables in the model and the average VIF value. These values indicate that there is apparently no multicollinearity between the variables because all the VIF coefficients and the VIF average are lower than 10. Therefore, none of the variables mentioned previously was removed from the model.
Bivariate Analysis
We carried out a bivariate analysis in order to see the potential relationships that each variable could form with the dependent variable of the study, which is investment. Table 13 shows the Kruskal Wallis test statistics between Investment and Type of share, and between Investment and Education level. We used this test because these variables have more than one dummy variable and because the data does not comply with the assumptions of the parametric tests.
|
Table 13 - Kruskal Wallis Test |
|||
|
Statistics |
Investment and Type of share |
Investment and Education level |
Investment and Income |
|
Chi-squared |
2.4180 |
3.7540 |
12.8650 |
|
Degree of freedom |
3.0000 |
2.0000 |
2.0000 |
|
Asymptotic Signif. |
0.4900 |
0.1530 |
0.0020 |
|
Note. Source: Research results. |
|
||
The results of the Kruskal Wallis test show a significance higher than 0.05 for Type of share and for Education level in relation to Investment, which leads to there being apparently no difference between the different groups of Type of share and Education level in relation to investment. This means that the Type of share and Education level had no influence on the investment. However, in the case of investment and income, there was significant statistical relevant, which means that there may be a difference among the income groups in relation to the amount invested.
Table 14 shows the results of the Mann-Whitney test for Investment and Knowledge, Investment and Experience, and Sex and Investment. We used the Mann-Whitney test for these variables because they had only one dummy.
|
Table 14 - Mann-Whitney Test for Investment |
|||
|
Statistics |
Knowledge |
Experience |
Sex |
|
Mann-Whitney’s U |
16860.5000 |
16155.500 |
17701.5000 |
|
Wilcoxon W |
35775.5000 |
47031.500 |
33811.5000 |
|
Z |
-1.3720 |
-0.5700 |
-0.2720 |
|
Asymptotic Signif. (Bilateral) |
0.1700 |
0.5690 |
0.7660 |
|
Note. Source: Research results. |
|||
Similarly to what happened with the Kruskal Wallis test results for other variables, the categories knowledge, experience and sex did not show a potential association with the amount of money invested by the research participants, because their significance is lower than 0.05.
Table 15 shows the results of the Spearman’s correlation to test the apparent relationship between investment and age
.
|
Table 15 - Results of the Spearman Correlation for Investments and Age |
|||
|
|
|
Age |
Investment |
|
Age |
Correlation Coefficient |
1.0000 |
-0.1630** |
|
|
Sig. (bilateral) |
. |
0,003 |
|
Investment |
Correlation Coefficient |
-0.1630** |
1.000 |
|
|
Sig. (bilateral) |
0.0030 |
. |
|
Note. ** Correlation is significant at the level 0.01 (bilateral). Source: Research results. |
|||
In this case, the significance of the test was lower than 0.05, which means that there is an association between the variables Age and Investment. This relationship will be tested in the multiple regression in the next section in order to verify whether these bivariate associations presented here persist in the multiple regression.
Regression Analysis
Table 16 contains the estimated results of the multiple regression applied to all the variables of the study, keeping in mind that investment was the dependent variable, type of share was the main explanatory variable, and the rest of the variables were considered control variables.
|
Table 16 - Multiple Regression Results |
||||||||
|
Variables |
Coefficient |
Standard error |
Z |
P>Z |
[95% Confidence interval] |
|||
|
TYP 1 |
1505.73 |
4148.034 |
0.36 |
0,717 |
-6655.725 |
9667.186 |
||
|
TYP 2 |
-3619.023 |
4085.274 |
-0.89 |
0,376 |
-11656.99 |
4418.949 |
||
|
TYP 3 |
431.4592 |
4089.76 |
0.11 |
0,916 |
-7615.339 |
8478.258 |
||
|
EDU 1 |
-225.8952 |
4160.127 |
-0.05 |
0,957 |
-8411.143 |
7959.352 |
||
|
EDU 2 |
471.8811 |
6808.721 |
0.07 |
0,945 |
-12924.6 |
13868.36 |
||
|
INC 1 |
3367.982 |
4047.121 |
0.83 |
0,406 |
-4594.921 |
11330.88 |
||
|
INC 2 |
-2648.389 |
3623.434 |
-0.73 |
0,465 |
-9777.669 |
4480.891 |
||
|
EXP |
470.1525 |
3920.078 |
0.12 |
0,905 |
-7242.788 |
8183.093 |
||
|
KNO |
2155.531 |
3709.277 |
0.58 |
0,562 |
-5142.648 |
9453.71 |
||
|
SEX |
-2589.335 |
3025.043 |
-0.86 |
0,393 |
-8541.252 |
3362.581 |
||
|
AGE |
-528.8507 |
287.0252 |
-1.84 |
0,066 |
-1093.586 |
35.88505 |
||
|
Breusch-Pagan/Cook-Weisberg Test |
0.0837 |
N 326 |
|
|||||
|
Shapiro-Wilk W-Test 0.0000 |
0.0000 |
R 0.0392 |
|
|||||
|
|
|
|
|
|||||
|
Note. Source: Research results |
|
|
|
|||||
According to the Shapiro-Wilk test, the data did not reveal normality, and according to the Breusch-Pagan/Cook-Weisberg test, there is no heteroscedasticity in the data presented. The results of the multiple regression showed that there is no relationship between Investment and the Type of share, showing that the type of share or the investment scenario does not represent an association with the amount of money invested in the share. The only variable that proved to be significant in relation to investment was age, at a level of 10% and with an inverse relationship. This means that older (mature) people tend to invest less resources, which may indicate a more conservative profile as the individual’s age increases.
Therefore, we can reject the three hypotheses of this research that indicated that sustainability, transparency or both had an influence in the investor’s decision-making. These results are contrary to the research of Alves and Borba (2010), Borba et al. (2012), Kaufmann and Weber (2013), and Milne and Patten (2002). This means that, for the data in this study, information on sustainability and transparency does not affect decision-making for investments. To add validity to the results, the regression was run again with the bootstrap technique with 10,000 samples, but the same results persisted.
These findings may be explained by the results of Santos and Barros (2011), which reveal that the decision-making process for investments is affected by different factors such as perception, personality and capacity of evaluation. Such circumstances may indicate why sustainability and transparency were not relevant, due to the fact that we are not completely rational.
The results of this study could also be justified by the literature that indicates that sustainability and transparency are important in firms, in the corporate decision-making process and in the valuation of shares, but when it comes to the decision-making process of individual investors, other characteristics such as the history of returns, investment decisions of other investors, specialized press or stock exchange bulletins are the aspects that really affect the investor’s decision-making, according to Khan et al. (2017).
FINAL REMARKS
This study sought to investigate the potential effects sustainability and transparency might have on the decision-making of investors at the moment when they allocate their resources in variable income (shares). To that end, an opinion survey was conducted through a questionnaire in which the respondents were shown information regarding a fictional share, separated into 4 different groups with additional information regarding to the share related to transparency, sustainability, both, or none. Faced with this situation, the participants indicated an amount of money that they would be willing to invest in this share. The goal was to analyze the existence of statistical differences between the amounts invested in each scenario and the exposure to additional information related to sustainability and transparency, following the methodology used in the studies of Alves and Borba (2010), Borba et al. (2012) and Milne and Patten (2002).
The questionnaire had 383 valid responses from people who live mostly in the region of influence around UFU and are undergraduate and/or graduate students in the accounting, business administration and information management courses at the university and, therefore, have basic knowledge about finance.
The theory indicates that sustainability and transparency should be factors that influence the investor’s decision-making, according to Borba et al. (2012), Kaufmann and Weber (2013), and Milne and Patten (2002). However, in light of the results obtained in the Kruskall Wallis Tests, it was found that there is no difference between the amounts invested by each of these groups, which contradicts the results of the authors mentioned above. Furthermore, it was found through multiple regression that there is no relationship between the amount invested and the type of share (investment scenarios with or without sustainability/transparency). However, an inverse relationship was perceived between the age of respondents and the amount invested by them, indicating that older people invested less, regardless of the scenarios presented.
To justify this phenomenon, according to Khan et al. (2017), investors tend to talk about the importance of sustainability and transparency of firms for decision-making; however, in practice, people tend to consider the history of returns, investment decisions of other investors, specialized press or stock exchange bulletins as the main factors for making their investment decisions. Additionally, the decision-making process is affected by factors that do not correspond solely to the information about the share and are related to the way in which people analyze and perceive the information according to Santos and Barros (2011), often making irrational decisions.
This research contributed to the study of Brazilian investors and their decision-making process when making investments. It adopted a methodology that is not often used in corporate finance, seeking to connect the theory to the financial reality in the context of the Triângulo Mineiro region in Minas Gerais, Brazil, which makes the study regional in nature. In addition, this attempted to reduce the gap between modern finance theory and its real-life execution as explained by Kimura et al. (2006). Another important fact is that the methodology used in this research was evaluated on several occasions by stockbrokers with participation and experience in the stock market, which led to a closer approximation of the scenarios to the reality of the market.
The main limitations of the research include the difficulty in accessing individual investors operating in the Brazilian capital market and the logistical difficulty that made it impossible to carry out a comparative analysis between investors from different regions in Brazil. For future studies, we recommend addressing topics related to sustainability and finance such as corporate social responsibility or social issues that impact firms. We also suggest applying the methodology in other regions of Brazil or even other countries to make comparisons between the results.
.
REFERENCES
ALMEIDA, A.; CUNHA, D. Estudo do mercado brasileiro de renda fixa e o perfil do investidor brasileiro. [s.l.] Universidade Federal do Rio de Janeiro, 2017.
ALVES, J.; BORBA, J. A relevância da informação contábil ambiental para a tomada de decisão de investimento: um estudo experimental. Contabilidade, Gestão e Governança, v. 12, n. 2, p. 44–57, 2010.
ALVES, T. Perfil e comportamento do investidor entre os comerciantes da região do Vicente Pires. [s.l.] Centro Universiário de Brasília, 2012.
B3. Índice de sustentabilidade empresarial ( ISE ) índice de sustentabilidade empresarial ( ISE ). Disponível em: http://www.bmfbovespa.com.br/pt_br/produtos/indices/indices-de-sustentabilidade/indice-de-sustentabilidade-empresarial-ise.htm.
BARAKAT, S. et al. Associação entre desempenho econômico e índice de sustentabilidade empresarial da bolsa de valores de São Paulo. Gestão & Regionalidade, v. 32, n. 95, p. 127–142, 2016.
BARBERIS, N.; THALER, R. A survey o behavioral finance. Handbook of the Economic of Finance, p. 1052–1121, 2002.
BODHANWALA, S.; BODHANWALA, R. Does corporate sustainability impact firm profitability? Evidence from India. Management Decision, 2018.
BOGEA, F.; BARROS, L. Processo de tomada de decisão do investidor individual brasileiro no mercado acionário nacional: um estudo exploratório enfocando o efeito disposição e os vieses da ancoragem e do excesso de confiança. Gestão & Regionalidade, v. 24, n. 71, p. 6–18, 2008.
BORBA, J. A. et al. Informações contáveis ambientais na percepção de analistas investidores e professores de finanças. Revista de Gestão Social e Ambiental, v. 6, p. 168–182, 2012.
BUSHMAN, R. M.; PIOTROSKI, J. D.; SMITH, A. J. What determines coporate transparency ? Journal of Accounting Research, v. 42, n. 2, p. 207–252, 2004.
COTRIM, B. Vieses cognitivos e o investidor individual brasileiro: uma análise da intensidade de vieses em decisões de investidores. [s.l.] Universidade Federal de Uberlândia, 2014.
DUXBURY, D. Behavioral finance: insights from experiments I: theory and financial markets. Review of Behavioral Finance, p. 78–96, 2015.
FIELD, A. Descobrindo a Estatística usando o SPSS. 2. ed. Porto Alegre: [s.n.].
GASPAR, R.; OSÉS, J. Avaliação do perfil do pequeno e médio investidor adequado à modalidade de fundo. Ciências Sociais em Perspectiva, v. 10, n. 6, p. 149–162, 2007.
HAUBERT, F.; DE LIMA, M.; HERLING, L. Behavioral finance : a study based on the theory of the prospectus and investor. Revista Eletrônica de Estratégia & Negócios, v. 5, n. 2, p. 171–199, 2012.
HENDRIKSEN, E. S.; VAN BREDA, M. F. Teoria da Contabilidade. 1. ed. [s.l: s.n.].
HIGGINS, C.; TANG, S.; STUBBS, W. On managing hypocrisy : The transparency of sustainability reports. Journal of Business Research, 2019.
JUNIOR, I.; SOUZA, E.; SANTOS, A. Investimento Financeiro: Uma análise do perfil investidor dos unicersitários do recôncavo da Bahia. Revista de Gestão e Contabilidade da UFPI, v. 2, n. 2, p. 96–114, 2015.
KAHNEMAN, D.; TVERSKY, A. Prospect Theory: an Analysis of Decision Under Risk. The Econometric Society, v. 47, n. 2, p. 263–291, 1979.
KAUFMANN, C.; WEBER, M. Sometimes less is more - The influence of information aggregation on investment decisions. Journal of Economic Behavior and Organization, v. 95, p. 20–33, 2013.
KHAN, M. T. I.; TAN, S. H.; CHONG, L. L. Information sources and investing decisions – a path modeling approach. Managerial Finance, v. 43, n. 8, p. 928–947, 2017.
KIMURA, H.; BASSO, L.; KRAUTER, E. Paradoxos Em Finanças: teoria moderna versus finanças comportamentais. Fórum, v. 46, n. 1, p. 41–58, 2006.
LAVILLE, E. A Empresa Verde. São Paulo: Bei Editora, 2009.
LIN, Z.; LIU, M.; NORONHA, C. The impact of corporate governance on informative earnings management in the chinese market. A Journal of Accounting, Finance and Business Studies, p. 1–42, 2016.
LUPPE, M. R.; ANGELO, C. F. As Decisões De Consumo E a Heurística Da Ancoragem: Uma Análise Da Racionalidade Do Processo De Escolha. Revista de Administração Mackenzie, v. 11, n. 6, p. 81–106, 2010.
MAUSS, C.; DELATORRE, A. Perfil dos investidores em renda variável na cidade de Profile of investors in equities in the city of Carazinho/RS . Revista Eletrônica Saber Contábil, v. 2, n. 1, p. 103–116, 2012.
MILNE, M. J.; PATTEN, D. M. Securing organizational legitimacy: An experimental decision case examining the impact of environmental disclosures. Accounting, Auditing & Accountability Journal, v. 15, n. 3, p. 372–405, 2002.
NAIR, R. et al. Corporate social responsibility disclosure and financial transparency : Evidence from India. Pacific-Basin Finance Journal, v. 56, p. 330–351, 2019.
PAIVA, L. et al. Practices of socio-environmental responsibility and performance in small and mid-sized Brazilian firms. Gestão & Regionalidade, v. 35, n. 106, p. 86–107, 2019.
PAPADOVASILAKI, D. et al. How important are early investment experiences on subsequent investment decisions? A laboratory experiment on asset allocation. Managerial Finance, v. 41, n. 6, p. 582–590, 2015.
PARABONI, A. L. et al. The relationship between sentiment and risk in financial markets. BAR - Brazilian Administration Review, v. 15, n. 1, p. 1–15, 2018.
PIMENTA, D.; BORSATO, J.; RIBEIRO, K. Um estudo sobre a influência das características sociodemográficas e do excesso de confiança nas decisões dos investidores, analistas e profissionais de investimento à luz das finanças comportamentais. REGE Revista de Gestão, v. 19, n. 2, p. 261–278, 2012.
RAMBO, A. C. O perfil do investidor e melhores investimentos: da teoria à prática do mercado brasileiro. [s.l.] Universidade Federal de Santa Catarina, 2014.
RIBEIRO, F. et al. Responsabilidade social corporativa e o desempenho financeiro no setor de energia elétrica : um estudo com modelo de dados em painéis. Gestão & Regionalidade, v. 33, n. 33, p. 99, 2017.
RICCIARDI, V.; SIMON, H. K. What is Behavioral Finance? Business, Education & Technology Journal, v. 2, n. 2, p. 1–9, 2000.
ROLDAN, V.; ROCHA, R. O investidor brasileiro é conservador : uma pesquisa com os Docentes do Centro Ciências Administrativas da Universidade de Fortaleza The brazilian investor is conservative : a research with the professors of the Center of Administrative Sciences of the Un. Revista Ciências Administrativas, v. 24, n. 2, p. 21–30, 2004.
SANTOS, J. Reação e Previsão: Tipificação do comportamento dos investidores no mercado de ações brasileiro. [s.l.] Universidade de São Paulo, 2017.
SANTOS, J.; BARROS, C. O que determina a tomada de decisão financeira: razão ou emoção? Revista Brasileira de Gestão de Negócios, v. 13, n. 38, p. 663–679, 2011.
SCHÖNBORN, G. et al. Why Social Sustainability Counts : The Impact of Corporate Social Sustainability Culture on Financial Success. Sustainable Production and Consumption, v. 17, n. 1, p. 1–10, 2018.
SIMON, H. . Models of man. John Wiley and Sons, 1957.
STEINHORST, M. P.; BAHRS, E. Agricultural investors valuing sequences of monetary rewards – results of an experiment. Agricultural Finance Review, v. 74, n. 3, p. 379–396, 2014.
TAHIR, I.; BRIMBLE, M. Islamic investment behaviour. International Journal of Islamic and Middle Eastern Finance and Management, v. 4, n. 2, p. 116–130, 2011.
VIEIRA, S.; BATAGLIA, R.; SEREIA, V. Educação financeira e decisões de consumo, investimento e Poupança: uma análise dos alunos de uma universidade pública do norte do paraná. Revista de administração da Unimep (RAU), v. 9, n. 3, p. 61–86, 2011.
ZHOU, R.; PHAM, M. T. Promotion and Prevention across Mental Accounts: When Financial Products Dictate Consumers& Investment Goals. Journal of Consumer Research, v. 31, n. 1, p. 125–135, 2004.
[1] Bacharel em Administração de Emrpesas pelo Tecnológico de Costa Rica (2016). Mestre em Administração pela Universidade Federal de Uberlândia (2019). Universidade Federal de Uberlândia -Brasil. E-mail: carr.dannie@gmail.com
[2] Doutora em Administração pelo Centro de Pós-Graduação e Pesquisas em Administração da Universidade Federal de Minas Gerais (2012), com período sanduíche no Instituto Superior de Economia e Gestão da Universidade Técnica de Lisboa. Mestre em Administração pela Universidade Federal de Uberlândia (2005). Professora Adjunta na Faculdade de Gestão e Negócios da UniversidadeFederal de Uberlândia, na área de Finanças. Professora do Programa de Pós-Graduação em Administração (PPGA) da FAGEN/UFU, na Linha Finanças e Controladoria. Universidade Federal de Uberlândia, Brasil. E-mail: fmacielpeixoto@gmail.com
[3] Professor Adjunto da Faculdade de Gestão e Negócios (FAGEN) da Universidade Federal de Uberlândia (UFU). Professor do Programa de Pós-Graduação em Administração (PPGA) da FAGEN/UFU. Coordenador do MBA em Gestão Empresarial da FAGEN/UFU. Doutor em Administração pela Universidade Federal de Minas Gerais (UFMG), com período sanduíche no Instituto Superior de Gestão e Economia (ISEG) da Universidade Técnica de Lisboa (UTL), em Portugal - bolsista CAPES. Mestre em Administração pela UFU, MBA em Gestão Estratégica de Marketing pela Fundação Getúlio Vargas (FGV) e graduado em Administração pela UFU. Universidade Federal de Uberlândia, Brasil. E-mail: andre.fagundes@ufu.br
[4] Doutoranda em Contabilidade Financeira pela Faculdade de Ciências Contábeis da Universidade Federal de Uberlândia (2018 a 2021). Mestra em Gestão Financeira e Controladoria pela Faculdade de Gestão e Negócios da Universidade Federal de Uberlândia (2016). Especialista em Gestão Financeira e Controladoria pelo Serviço Nacional de Aprendizagem Comercial (2012). Docente na linha de finanças para a Universidade Federal de Uberlândia e para a Faculdade do Trabalho. Universidade Federal de Uberlândia, Brasil. E-mail: claudiamamede@yahoo.com.br